A 609 dispute letter is actually not a dispute but is simply a way of requesting that the credit bureaus provide you with certain documentation that substantiates the authenticity of the bureaus’ reporting.
Key takeaways
- A 609 dispute letter asks the credit bureaus to show the documentation behind an item on your credit report, not to remove it outright.
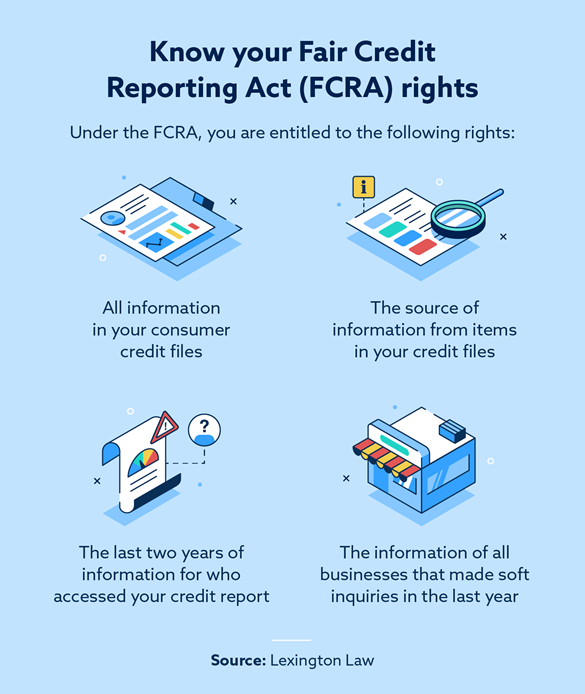
- The right to request that documentation comes from Section 609 of the Fair Credit Reporting Act (FCRA); the right to dispute inaccurate information comes from Section 611.
- If a bureau can’t verify an item within about 30 days, it’s required to remove that item from your report.
- A 609 letter can’t force the removal of accurate, verified information, including a bankruptcy or a confirmed late payment.
- If your letter doesn’t get results, options include a direct dispute with the furnisher, a goodwill letter or a CFPB complaint.
Why a 609 Letter Matters
A 609 letter matters because it puts you in a position to catch and correct costly mistakes before they affect your finances. Derogatory marks on your credit report, whether accurate or not, can make it harder to qualify for loans, rent a home or sign up for services, and even a single inaccurate late payment can drag down your score.
The Federal Trade Commission has found that roughly one in five Americans has an error on at least one of their credit reports, which is part of why understanding your right to request documentation matters.
- Ensures accountability. Requesting documentation puts the burden on the bureau to prove an item is accurate, rather than leaving that burden on you.
- Reveals errors. Reviewing the source and details behind an entry often surfaces mistakes, like a mismatched account or an outdated balance, that you wouldn’t otherwise catch.
- Triggers the 30-day rule. Once you request verification, the bureau generally has about 30 days to respond or remove the item.
- Protects your score. Regularly working to check your credit score can help you catch issues early, before they affect loan approvals, rental applications or job screenings.
Credit report errors are more common than most people realize, and they aren’t always obvious. Lexington Law’s advocates can review your full report, help you identify entries that may be inaccurate and put together requests like this on your behalf.
Does a 609 Dispute Letter Actually Work?
A 609 credit dispute letter can lead to an item’s removal, but only if the bureau can’t verify it. If the debt or account is accurate and the bureau can produce supporting documentation, the letter won’t result in a deletion, no matter how the request is worded. It doesn’t work as a way to erase accurate, verified information, including a bankruptcy, a confirmed late payment or an already-closed account that’s reporting correctly.
Because success depends entirely on whether the bureau can back up what’s on your file, how you write the letter and what you ask for matters. The next section walks through how to put one together so it has the best chance of getting a response.
How to Write a 609 Dispute Letter
Credit dispute letters that work follow a simple process you can do yourself.
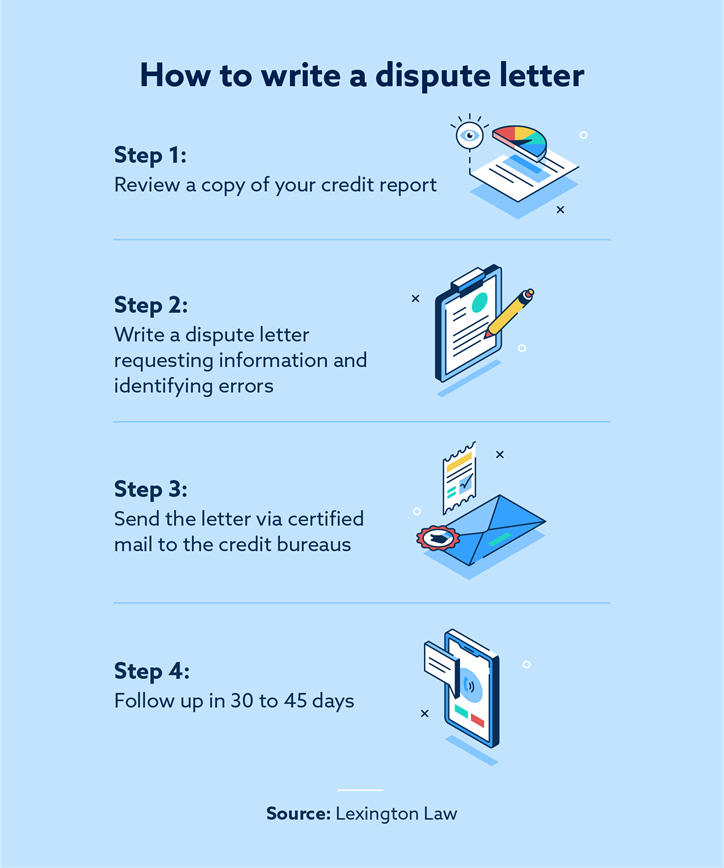
- Get a copy of your credit report. Request your report from each bureau (Equifax®, Experian® and TransUnion®) so you can see the positive and negative marks currently affecting your score.
- Collect your letter information. Include your name, address, phone number and date of birth, along with the following:
- A statement asserting your rights under the FCRA
- The credit bureau account numbers and account names in question
- A copy of your credit report with the specific items circled or highlighted
- A copy of your government-issued ID and a document showing proof of address
- Write your letter. Use the template below as a starting point, and clearly request removal of any information the bureau can’t verify.
- Follow up. Send the letter by certified mail so you receive a delivery receipt, then follow up by phone if you haven’t heard back within 30 to 45 days.
609 Letter Template
This 609 letter template covers the core language a 609 letter needs. Fill in your own account details and documentation before sending it.
[Your Name]
[Your Address]
[Your City, State, ZIP Code]
[Date]
[Credit Bureau Name]
[Bureau Address]
Re: Request for Verification Under Section 609 of the FCRA
To Whom It May Concern,
I am exercising my right under Section 609 of the Fair Credit Reporting Act to request information regarding the following item(s) listed on my consumer credit report:
[Account name(s) and account number(s)]
Per Section 609, I am entitled to see the source of this information, including the original document containing my signature.
As proof of my identity, I have enclosed copies of my [government-issued ID] and [proof of address]. I have also enclosed a copy of my credit report with the item(s) in question circled.
If you are unable to verify this account with the original documentation, please remove it from my credit report within 30 days, as required by law.
Sincerely,
[Your Name]
[Phone Number]
[Address, Social Security number (last 4 digits), date of birth]
What to Do if Your 609 Letter Doesn’t Get Results
Bureaus are legally required to investigate a request like this, but that doesn’t mean they’ll respond quickly, or at all, after a single letter. It’s common to send a request and hear nothing back within the 30-to-45-day window, especially if the bureau already considers the item verified.
If that happens, don’t assume you’re out of options. A handful of alternative approaches can pick up where a 609 letter leaves off.
Alternatives to a 609 Letter
If a 609 letter doesn’t get you anywhere, consider one of these approaches instead.
- Goodwill letters. A goodwill letter asks a creditor to remove an accurate but negative mark as a courtesy, typically after you’ve already paid off the account.
- Pay-for-delete letters. A pay-for-delete letter negotiates directly with a collection agency to have an account removed in exchange for payment, rather than requesting documentation.
- Debt validation letters. Sent within 30 days of first contact from a collector, this letter forces them to prove a debt is valid and theirs to collect before you pay anything.
- Direct dispute to the furnisher (Section 623). Instead of going through the bureaus, you can dispute directly with the bank or lender that reported the information.
- Traditional credit disputes (Section 611). This is the FCRA’s actual dispute process, letting you formally contest information you believe is inaccurate.
- CFPB complaints. If a bureau or furnisher isn’t responsive, filing a complaint with the Consumer Financial Protection Bureau can prompt a faster review.
- Work with an attorney. If your situation is complex, or you believe your rights under the FCRA have been violated, a consumer protection attorney, or Lexington Law’s team of advocates, can help you build a stronger case.
- Letter of explanation. If the issue is more about context than accuracy, a letter of explanation can help a lender understand your side without formally disputing the item.
Not every negative mark is worth disputing. If an item is accurate, focusing on how to pay off debt and letting it age off your report naturally may be the simpler path.
Remove False Derogatory Marks with Lexington Law Firm
A 609 dispute letter is a useful first step for finding out what’s really behind an item on your credit report, but it only works when the bureau can’t verify what it’s reporting. If you’re seeing negative items that don’t look right, it’s worth digging further before you assume there’s nothing you can do.
Our advocates can review your full credit report, help you identify entries that may be inaccurate or unfair and work with you to challenge them with the bureaus and creditors on your behalf. Start with a free credit assessment to see where your credit stands today.
Common Questions Related to 609 Dispute Letters
What’s the Difference Between 609 and 623 Dispute Letters?
A 609 letter requests documentation from the credit bureaus themselves, while a Section 623 dispute goes directly to the furnisher, the bank or lender that originally reported the information. Both can prompt a review, but a 623 dispute puts the burden of proof on the company that reported the item rather than on the bureau holding it.
What Are Some Valid Reasons to Dispute a Negative Credit Item?
Valid reasons to dispute an item include a mixed-up account that isn’t yours, a balance or payment history that doesn’t match your records, outdated information that should have aged off your report or an account affected by identity theft. If the issue is more about context than accuracy, a letter of explanation can sometimes help too. Lexington Law’s advocates can review your credit report and help you sort out which of your negative items are actually worth disputing before you send anything.
How Do You Get Things Removed From Your Credit Report?
Items come off your credit report when a bureau can’t verify them after a dispute, when they age past the FCRA’s reporting time limit (typically seven years) or when a creditor agrees to remove them voluntarily through something like a goodwill or pay-for-delete letter. There’s no way to have accurate, verified information removed early.
Note: Articles have only been reviewed by the indicated attorney, not written by them. The information provided on this website does not, and is not intended to, act as legal, financial or credit advice; instead, it is for general informational purposes only. Use of, and access to, this website or any of the links or resources contained within the site do not create an attorney-client or fiduciary relationship between the reader, user, or browser and website owner, authors, reviewers, contributors, contributing firms, or their respective agents or employers.