Key takeaways
- A hard inquiry happens when you apply for new credit and can cause a small, temporary dip in your score, while a soft inquiry never affects your score.
- The difference between hard inquiry and soft inquiry comes down to consent and visibility: hard inquiries require your permission and appear to other lenders, while soft inquiries can happen without you applying for anything and only you can see them.
- Both hard and soft inquiries typically stay on your credit report for about two years, though only hard inquiries are visible to lenders.
- Rate shopping for a mortgage, auto loan or student loan within a 14- to 45-day window is usually treated as a single hard inquiry, depending on the scoring model.
- If you spot a hard inquiry you don’t recognize, you can dispute it with the credit bureaus and the creditor that requested it.
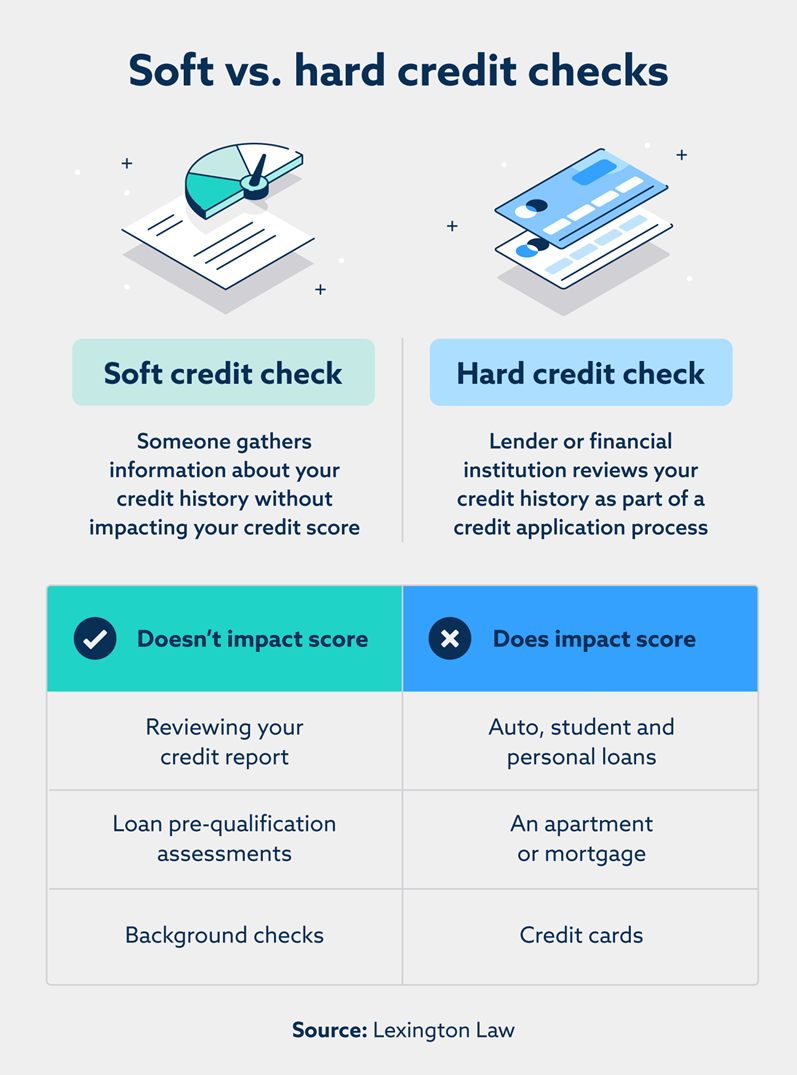
A hard versus soft inquiry comes down to one key distinction: a hard inquiry can temporarily lower your credit score, while a soft inquiry can’t touch it at all. Both happen when someone accesses your credit report, but the reason behind the request, and what it costs you, are very different. A soft inquiry might occur when a lender pre-approves you for an offer or when you check your own score, while a hard inquiry shows up when you formally apply for a loan, credit card or lease.
Credit checks exist because lenders need a way to gauge whether you can handle a new car payment, a mortgage or a credit line before they extend it. Understanding when each type of check applies, and when it can affect you, helps you apply for credit with more confidence and fewer surprises on your report.
This guide walks through the difference between a hard inquiry and a soft inquiry, how long each stays on your credit report, ways to limit the impact of hard pulls and what to do if you spot one you don’t recognize. Jump to the section you need most, or read straight through for the full picture:
What Is a Soft Credit Check?
A soft credit check, also called a soft pull or soft inquiry, pulls information from your credit report without affecting your credit score. Unlike a hard pull, the distinction usually comes down to intent: soft checks are informational, not tied to a specific credit application you’re actively pursuing. They can happen with or without your direct involvement, and lenders don’t need your explicit permission to run one.
- Checking your own credit. Reviewing your own report or score through your bank, a credit card issuer or a free credit monitoring service always counts as a soft inquiry.
- Pre-approved offers. Lenders and credit card companies often run a soft pull to see whether you qualify before sending a pre-approval offer in the mail or online.
- Employment background checks. Some employers review a modified version of your credit report as part of a background check, typically for roles that involve handling money.
- Apartment rentals. Landlords and property managers may run a soft check early in the screening process to get a general sense of your financial history.
- Existing account reviews. Credit card issuers periodically check your credit to decide whether to adjust your interest rate or credit limit on an account you already have.
- Buy now, pay later approvals. Many BNPL providers use a soft pull to approve you for a short-term installment plan at checkout.
So do soft pulls affect credit at all? No. Soft inquiries don’t suggest you’re taking on new debt, so scoring models don’t penalize you for them. They can appear on your own copy of your credit report for around two years, but only you can see them there. Lenders and creditors reviewing your file never see your soft inquiries, which is part of what separates a soft inquiry from a hard inquiry: the next type of check, which does leave a mark other lenders can see.
What Is a Hard Credit Check?
A hard credit inquiry, pull or check occurs when a lender reviews your credit history because you’ve formally applied for credit, and it can lower your score by a few points. It isn’t a derogatory mark on your report, but scoring models treat it as a small signal of new financial risk since you’re actively seeking to take on debt. Lenders request a hard pull to set the terms of a credit offer based on your creditworthiness, and the dip it causes typically fades within a few months.
- Applying for loans. Auto, personal and student loan applications all trigger a hard pull so the lender can confirm you qualify for the terms offered.
- Credit card applications. Opening a new card means the issuer checks your credit to set your limit and interest rate.
- Credit limit increases. Some issuers run a hard pull when you request a higher limit on an existing card, rather than relying on a soft check.
- Apartment leases. Later in the rental screening process, once you’ve moved past an initial soft check, a landlord may run a full hard inquiry to finalize your lease.
- Setting up utilities. Utility and cell phone providers sometimes check your credit before activating new service without a deposit.
A hard credit check matters most when you’re accumulating several inquiries in a short window. A single hard inquiry rarely moves the needle much, but multiple hard pulls close together can make lenders view you as a higher credit risk, since it may look like you’re taking on more debt than you can manage.
Pro tip: If you’re rate shopping for a mortgage, auto loan or student loan, scoring models typically group multiple hard inquiries of the same type into one if they fall within a set window, often 14 to 45 days depending on the model. That means you can compare offers from a few lenders without taking a separate hit for each application.
How Long Do Hard and Soft Inquiries Stay on Your Credit Report
Both hard and soft inquiries typically stay on your credit report for about two years, but who can see them, and for how long they matter, differs. A hard inquiry can affect your score for up to a year, though most scoring models weigh it most heavily in the first few months, since recent inquiries are treated as more relevant than older ones.
Scoring models don’t all handle this the same way. FICO® generally stops factoring inquiries into your score after 12 months, even though they remain visible on your report for two years, while VantageScore® models can weigh them somewhat differently depending on the version. When you’re comparing credit report entries for a soft pull versus a hard pull, only the hard inquiry shows up to lenders and creditors who pull your file.
Soft inquiries, by contrast, sit quietly on your report the whole time without affecting your score or your standing with lenders. They remain visible only to you, which is why hard inquiries and soft inquiries can look identical in your own credit monitoring app, even though only one type carries any real weight with lenders.
How to Reduce the Impact of Hard Credit Pulls
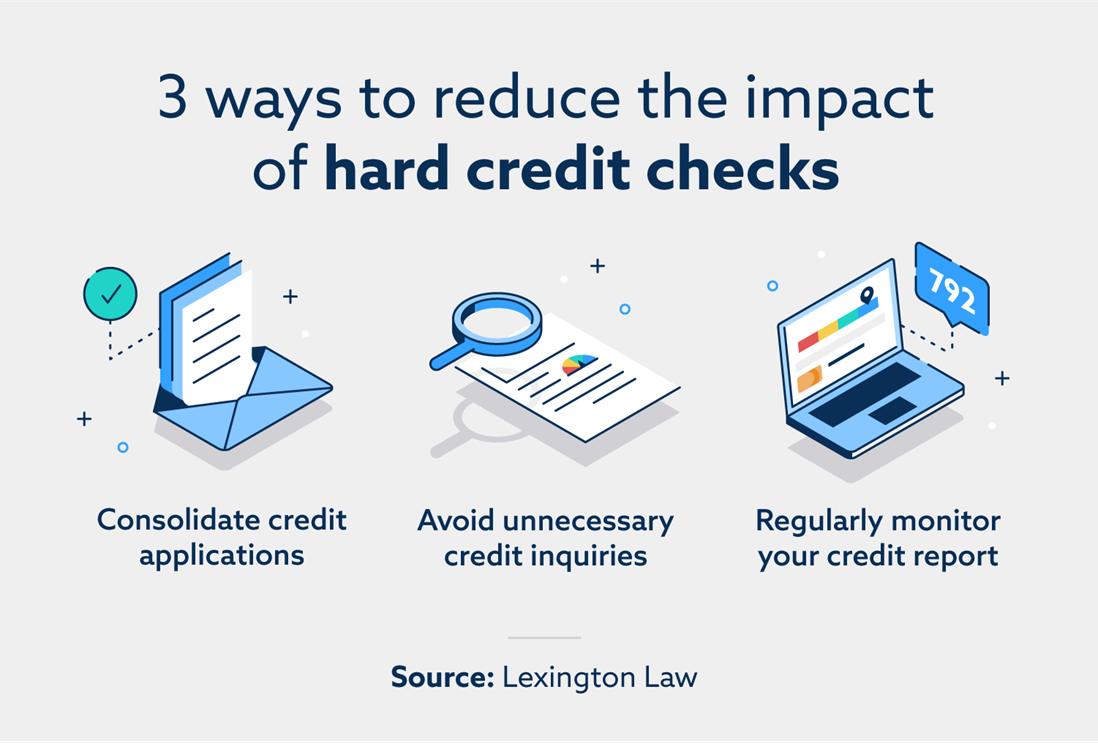
You can’t avoid the impact of a hard credit check entirely once you apply for credit, but a few habits can help limit how much it affects your score over time.
- Consolidate your applications. Scoring models typically treat multiple inquiries of the same loan type as a single inquiry when they fall within a short rate-shopping window, usually 14 to 45 days.
- Avoid unnecessary credit applications. Being selective about which cards or loans you apply for helps you steer clear of inquiries that don’t add much value.
- Space out applications for different credit types. A mortgage inquiry and a credit card inquiry aren’t grouped together, so spacing unrelated applications out reduces how many hard pulls land on your report at once.
- Check your eligibility first. Many lenders offer a pre-qualification step that only requires a soft pull, letting you see likely terms before committing to a hard inquiry.
- Monitor your credit report regularly. Reviewing your report often helps you catch errors or unauthorized hard inquiries before they sit unchallenged for months.
Not every hard inquiry on your report is one you recognize right away. If you come across one you didn’t authorize, you have the right to challenge it, which is where disputing comes in.
How to Dispute a Hard Credit Inquiry
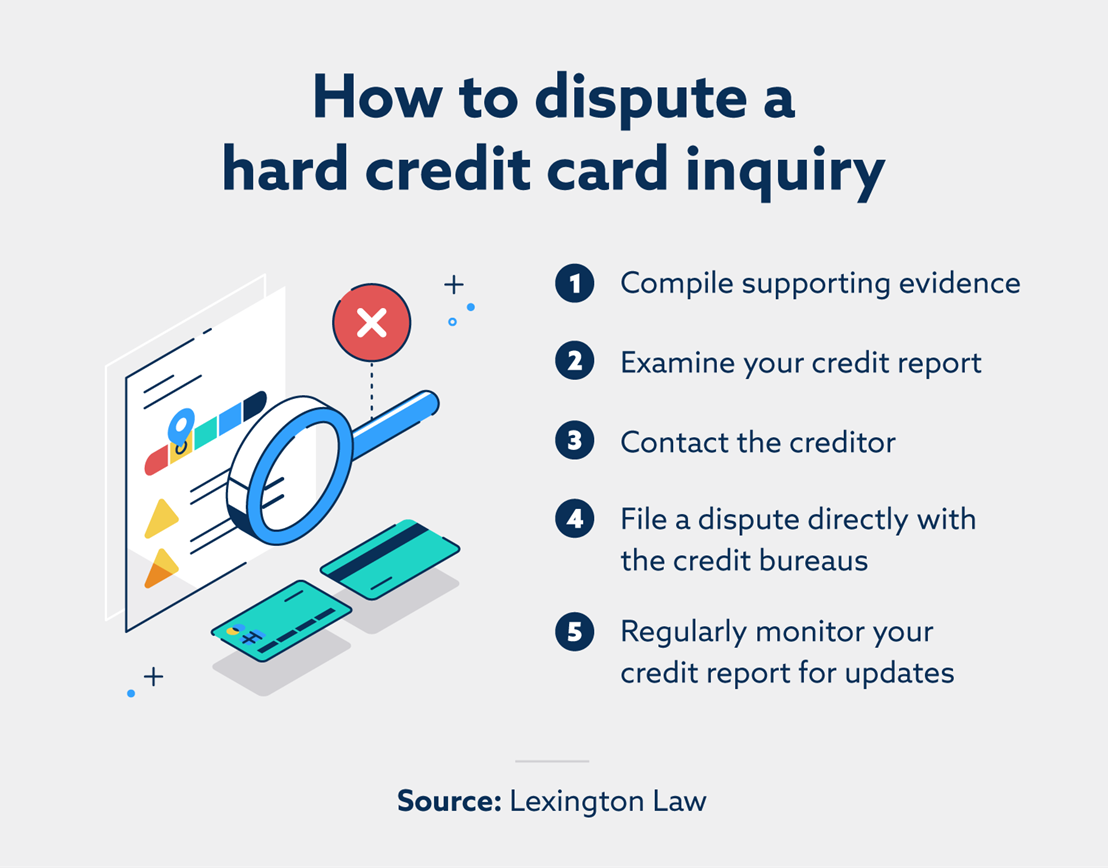
If you believe a hard inquiry on your report is inaccurate or unauthorized, disputing it protects both your score and the accuracy of your file. The process generally follows four steps.
- Compile your evidence. Gather your credit reports, any correspondence with the creditor and anything that supports your claim that the inquiry wasn’t authorized.
- Examine your credit report. Pinpoint the exact inquiry in question, including the date and the name of the company that requested it.
- Contact the creditor. Reach out to the company that made the inquiry and ask them to explain or remove it, providing identifying documents if requested.
- Dispute with the credit bureaus. If the creditor doesn’t respond or cooperate, file a dispute directly with the bureau online, by mail or by phone, laying out why you believe the inquiry is incorrect.
Once you’ve filed, the bureau investigates by contacting the creditor for verification. If the creditor can’t confirm the inquiry within the standard 30-day window, the bureau removes it from your report.
After a dispute closes, keep monitoring your report to confirm the inquiry was actually removed. If it resurfaces, contact the bureau again for an explanation and be ready to submit additional documentation.
Pro tip: If a hard inquiry is accurate but you’d still like it reconsidered, for example after a denied application you later resolved, a Goodwill letter to the creditor can sometimes prompt a review, though it isn’t a guaranteed fix.
See How Lexington Law Firm Can Help
Knowing the difference between a hard inquiry and a soft inquiry helps you apply for credit with more confidence, but an unauthorized or inaccurate hard pull can still slip through and sit on your report for months if it goes unchallenged. Similarly, there may be other negative items on your report that are hurting your credit without your knowledge. Our advocates can help you identify and challenge inaccurate or unfair entries, so your report reflects only what’s actually yours as you work to build credit habits that keep future hard inquiries to a minimum.
If you’re not sure where to start, a Free credit assessment is a good first step. We’ll review your credit report, work with you to identify potentially inaccurate items and walk you through how to dispute them with the bureaus and creditors, so you can move forward with fewer surprises the next time you apply for credit.
Hard vs. Soft Inquiry FAQs
Here are quick answers to the questions that come up most when weighing a hard inquiry vs soft inquiry on your credit report.
Do multiple inquiries count as one?
Multiple hard inquiries of the same type, like several auto loan applications, can count as a single inquiry if they happen within a set rate-shopping window. This deduplication window varies by scoring model, from 14 days under VantageScore® to 45 days under FICO®, letting you compare offers without stacking penalties for each application.
Does a soft inquiry show up on your credit report?
A soft inquiry does show up on your own copy of your credit report, but only you can see it there. Lenders and creditors reviewing your file for a credit decision never see your soft inquiries, and they don’t affect your score.
Can you have too many hard inquiries?
Too many hard inquiries in a short period can make lenders view you as a higher credit risk, even though each individual pull only costs a few points. Spacing out applications for different types of credit helps keep your inquiry count from stacking up unnecessarily.
Do hard inquiries affect all three credit bureaus?
A hard inquiry typically only appears on the credit report of the bureau, Experian®, TransUnion® or Equifax®, that the lender pulled from, not all three automatically. Which bureau gets pulled depends on the lender’s preference or the specific product you applied for.
What information is found on a soft credit check?
A soft credit check generally shows a general summary of your credit history, including your payment patterns, existing accounts and overall credit standing, without a full deep dive into every account detail. It gives the requester a broad sense of your reliability without functioning as a formal credit decision.
Can you fail a soft credit check?
You can’t fail a soft credit check in the way you might fail a formal application, since it’s informational rather than a lending decision. A soft pull can still reveal issues, like a low score or past delinquencies, that might affect whether you’re offered pre-approval or favorable terms later.
Note: Articles have only been reviewed by the indicated attorney, not written by them. The information provided on this website does not, and is not intended to, act as legal, financial or credit advice; instead, it is for general informational purposes only. Use of, and access to, this website or any of the links or resources contained within the site do not create an attorney-client or fiduciary relationship between the reader, user, or browser and website owner, authors, reviewers, contributors, contributing firms, or their respective agents or employers.